
Capital is moving ridiculously fast in 2026. One day a hedge fund drops a billion dollars into emerging market bonds, and the next day it pulls everything out because of a minor inflation tick.
Investors staring down this kind of volatile market inevitably ask themselves how does FDI differ from foreign portfolio investment flows, especially when trying to figure out where the smart money is actually staying.
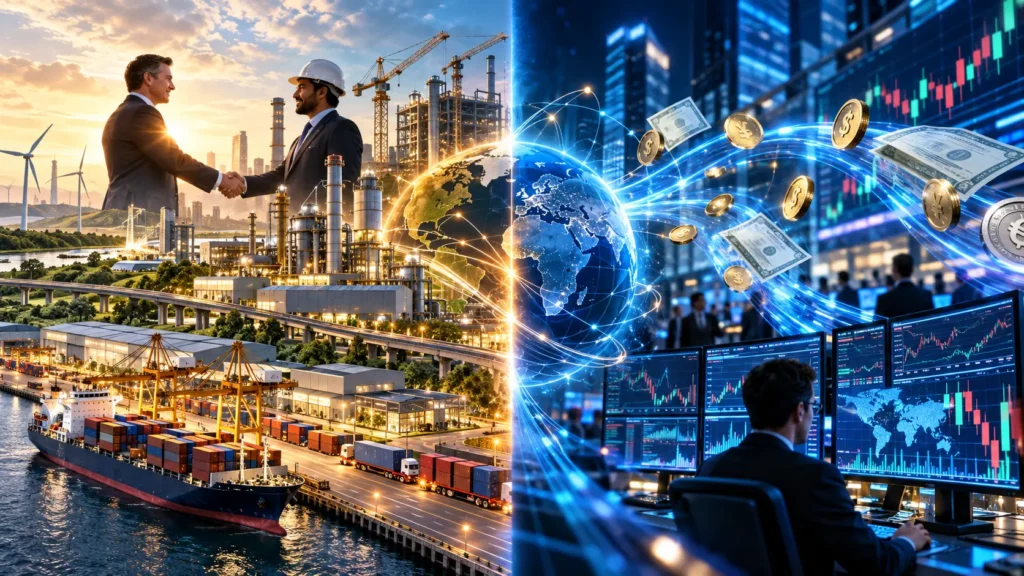
It boils down to a simple reality. One is a long-term marriage. The other is a quick date.
Defining the Heavy Lifting of FDI
Foreign Direct Investment isn’t about playing the stock market. It is the physical, grinding work of building real assets.
We are talking about pouring concrete for semiconductor plants, acquiring local subsidiaries, and demanding actual board seats.
Suppose a global tech giant decides to build a big AI infrastructure hub in India.. that is FDI. They are buying management control and locking their capital away for the long haul.
The current 2026 situation proves exactly how sticky this money is. Countries are fiercely competing to attract it because FDI brings jobs, proprietary technology, and a massive boost to domestic manufacturing.
You cannot liquidate a data center or a gigafactory from a brokerage app on your phone. Once the money is committed, the investor is strapped in for the ride.
The Liquid Nature of Foreign Portfolio Investment Flows
Foreign Portfolio Investment is a completely different beast. This is purely financial capital chasing yields.
Investors buy up stocks, government bonds, and mutual funds without the slightest desire to actually run the companies they are investing in. It is fast, highly liquid, and notoriously flighty.
Just look at the capital changes we’ve seen recently. Billions in FPI have rapidly exited Asian equities, specifically in markets like South Korea and India, transforming hard into bonds to chase safer returns.
These portfolio flows operate under the ten percent ownership threshold. The moment an investor crosses that line, regulators generally reclassify the money as FDI.
Until then, FPI remains the ultimate “hot money.” It provides crucial liquidity to global stock exchanges but will sprint for the exit the second geopolitical risks flare up or interest rates shift.
Where FDI and FPI Differ on the Balance Sheet
If you put them side by side.. the difference is obvious. It starts with control. FDI investors dictate company strategy, fire CEOs, and drive operational changes. FPI investors just sit back and collect dividends or ride asset price inflation.
Then there is the liquidity factor. Portfolio investments can be dumped in milliseconds by algorithmic trading desks. Direct investments take months or even years to unwind through complex mergers and acquisitions.
The economic footprint is just as skewed. Direct investment fundamentally expands a country’s productive capacity. It builds supply chains from scratch. Portfolio flows just inflate the value of existing financial assets.
While emerging markets desperately need FPI to deepen their capital markets and fund government debt, they know an overreliance on it leaves their currency painfully exposed to sudden panic selling.
Watching these two indicators tells you exactly where the global economy is heading. Plunging FPI means investors are panicked and hoarding cash. Surging FDI means corporations are genuinely optimistic about a region’s ten-year horizon.